New Zealand still has no crypto law. The FMA wants one
The market regulator says the country needs a purpose-built legal framework for virtual assets or risks falling behind. Here’s how crypto is regulated today, what the FMA is doing in the meantime, and what it means for you.
By Eli Hylands
· 3 min read
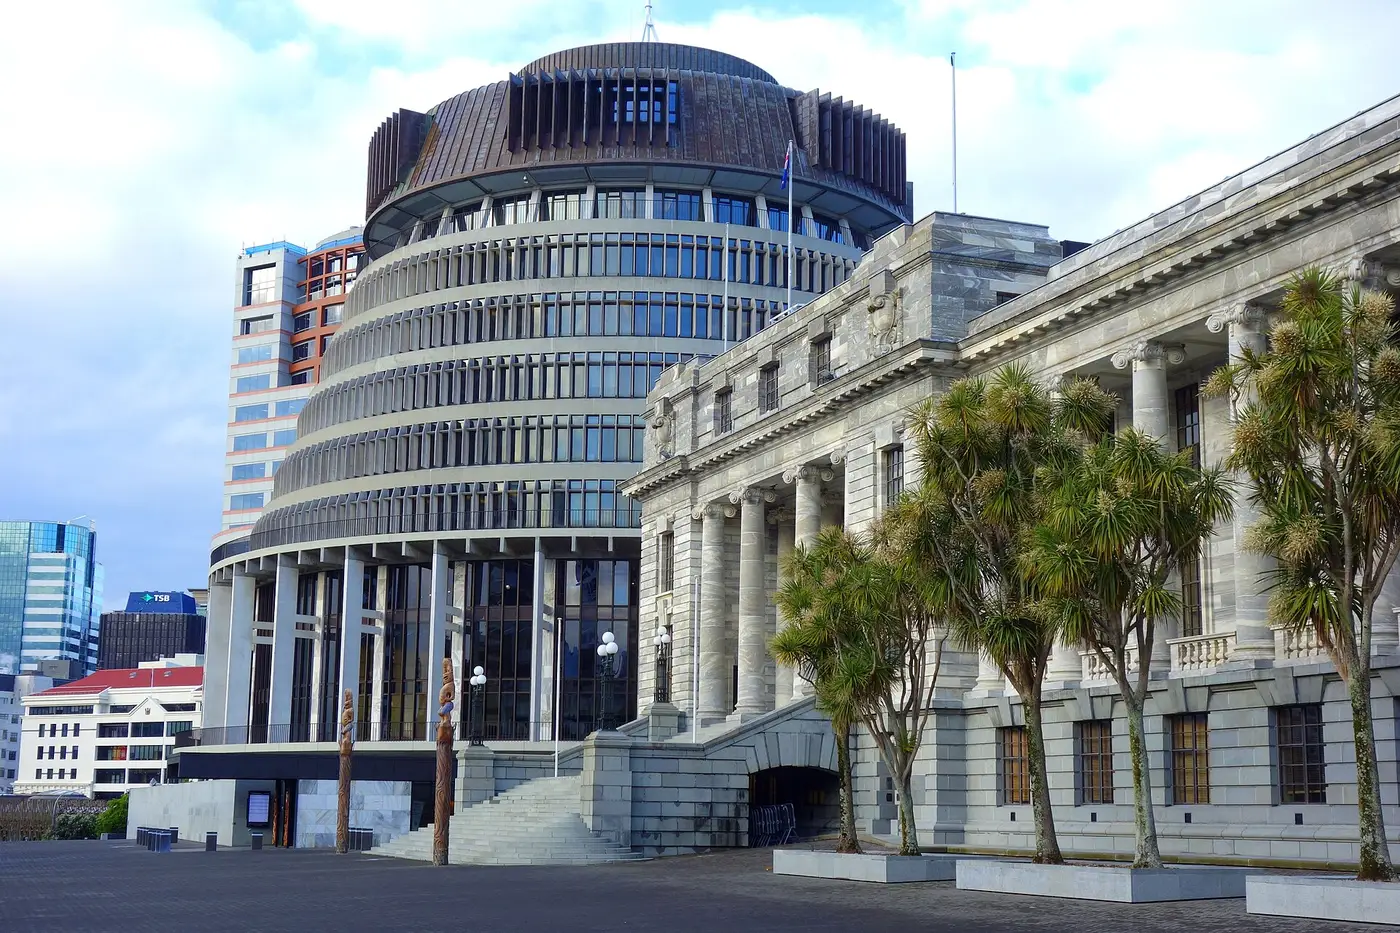
New Zealand’s financial markets regulator wants Parliament to write a law for crypto. In March, the Financial Markets Authority said the Government needs to introduce “a purpose-built and enduring legal framework for virtual assets”, NBR reported, warning that New Zealand risks falling behind Singapore, the United States and Europe on tokenisation and virtual assets.
The call came as the FMA published its response to a consultation on tokenisation, which acknowledged that today’s rules don’t give crypto service providers a clear licensing pathway. No bill has followed, and the Government hasn’t announced a timetable.
How crypto is regulated today
There is no crypto-specific licensing regime in New Zealand. Instead, crypto businesses are covered by a patchwork of general laws.
Most providers that serve New Zealanders must register on the Financial Service Providers Register, and those serving retail customers must belong to an approved dispute resolution scheme. Crypto businesses are also reporting entities under anti-money laundering law, which means they must verify customers’ identities, monitor transactions and report suspicious activity. Since 1 July 2026, the Department of Internal Affairs has been the sole supervisor for those rules.
The FMA’s own conduct rules apply only when a particular crypto-asset counts as a financial product, such as a debt security, a share or a derivative. That is decided case by case. General consumer law, including the Fair Trading Act’s ban on misleading conduct, applies throughout, and since April crypto platforms have also had to collect customer information for annual reports to Inland Revenue.
“Registration isn’t a licence, and it isn’t an FMA stamp of approval.”
What the industry told the regulator
The FMA’s tokenisation consultation, which opened in September 2025, drew submissions from across the sector. Submitters saw benefits including wider ways to raise capital, better market access and improved liquidity.
They also flagged risks, including the custody and control of virtual assets, cyber security, and fraud involving fake tokenised assets. A recurring concern was legal and regulatory uncertainty, made sharper by other countries moving to license crypto service providers.
What the FMA is doing in the meantime
Without new law, the FMA is using the tools it has. Its fintech sandbox pilot admitted six firms from 24 that expressed interest, and the FMA said in March that four had found a route to market. The first sandbox exemption and licence went to the Easy Crypto subsidiary behind the NZDD stablecoin, which the FMA later declared is not a financial product.
The FMA now plans an “on-ramp” licence, which would let innovative firms enter the market with restrictions that are lifted as they grow. Chief executive Samantha Barrass said the approach would help innovation and competition while balancing risks to consumers. No start date has been announced.
In May, the FMA published a report on the pilot, noting participants’ frustration with uncertainty, cost and the steep step up to full licensing. It set out an 18 to 24 month work plan whose priorities include a multi-year programme on virtual assets and payment service providers.
Why the FMA can’t fix it alone
The FMA can issue guidance, grant exemptions and decide whether a particular token is a financial product. It can’t create a new licensing regime for crypto businesses. That takes legislation.
Parliament has looked at the question before. In 2023, its Finance and Expenditure Committee completed an inquiry into crypto that put 22 recommendations to the Government. The Government’s 2024 response said it wanted to support industry growth and would keep the issues under review, but it didn’t commit to legislation. Whichever government forms after the 7 November election will decide whether to take up the FMA’s call.
What it means for you
Until there is a dedicated regime, how well you are protected depends largely on the provider you choose. Before using one, search the Financial Service Providers Register to confirm the business is registered, check which dispute resolution scheme it belongs to, and find out who holds your crypto.
Registration on the register isn’t a licence, and it doesn’t mean the FMA has approved or supervises the business. Crypto holdings aren’t bank deposits either, so the Depositor Compensation Scheme that protects bank savings isn’t designed to cover them.
This article is general information only and is not financial advice. Crypto-assets can be volatile, and blockchain transfers are generally irreversible.
Eli Hylands
Eli is the founder of Flow Crypto and editor of Flow News, covering crypto for New Zealanders.