ACT’s crypto pitch: no tax on gains held for more than a year
ACT’s digital economy plan would stop taxing gains on long-held personal crypto and exempt small purchases. Here’s what it proposes, and what the rules are today.
By Eli Hylands
· 2 min read
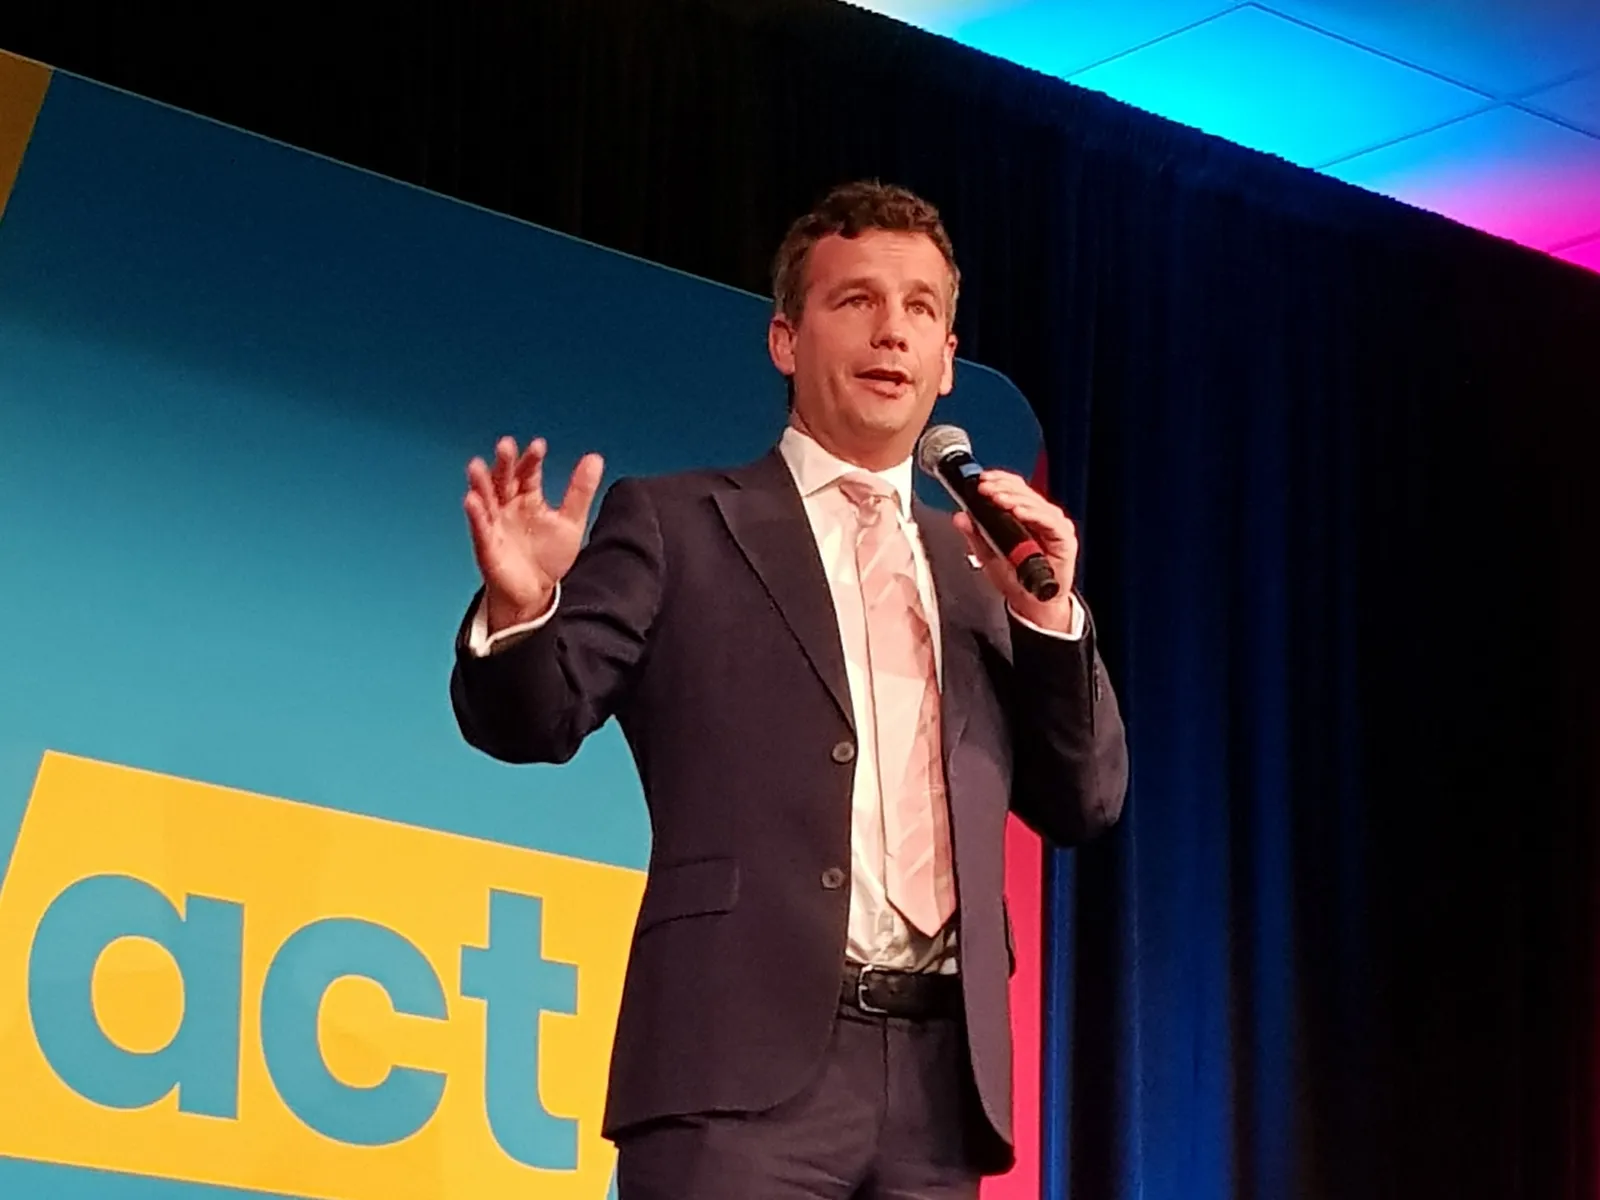
ACT has put crypto tax on the table ahead of the 7 November election. Its policy document, Unlocking New Zealand’s Digital Economy, published on 27 August, sets out six reforms to how digital assets and financial technology are taxed and regulated.
The headline change is a 12-month bright-line test for personal investment in digital assets. Deputy leader Nicole McKee said the plan would give everyday investors “certainty and simplicity”, RNZ reported, and leader David Seymour is campaigning on it.
What would change for investors
Under ACT’s proposal, gains on qualifying personal investments sold within 12 months would stay taxable. Gains on digital assets held for more than 12 months would not be taxed. Professional traders and businesses would remain under the existing tax rules.
ACT also proposes a tax exemption for low-value purchases made using digital assets, so someone paying for something small with crypto wouldn’t need to work out a gain or loss on it. The document doesn’t say what the low-value limit would be, or exactly which investments would qualify.
“Under ACT’s plan, how long you held crypto would matter more than why you bought it.”
The other four reforms
The rest of the plan is aimed at businesses. ACT says it would set clear legal and tax rules for tokenised securities and real-world assets, and a regulatory and tax framework for qualifying payment stablecoins: those fully backed by high-quality assets and redeemable for ordinary currency.
It would also create a proportionate sandbox where innovative financial firms could test products under supervision, and review whether regulatory settings are unnecessarily stopping legitimate businesses from getting access to banking.
What the rules are today
None of this is law. Today, Inland Revenue treats crypto-assets as a form of property for tax purposes, and the reason you acquired crypto matters: tax may apply if you bought it to sell or exchange, if you trade it, or if you use it in a profit-making scheme.
That purpose test is what ACT wants to replace. Its document argues that tax shouldn’t depend on subjective assessments of why someone bought a digital asset. Inland Revenue says around 355,000 New Zealanders use crypto, RNZ reported.
What happens next
ACT’s plan is a campaign promise. Any change to crypto tax would need to pass through Parliament, and ACT would need support from other parties to get it there. Until then, the current rules apply to any crypto you sell, before or after the election.
Whatever happens, keep records of what you bought, when, and for how much. They matter under today’s rules, and a holding-period test like ACT’s would rely on them too.
Flow News doesn’t endorse any political party. This article summarises ACT’s published proposal and doesn’t compare it with other parties’ policies.
This article is general information only and is not financial advice. Crypto-assets can be volatile, and blockchain transfers are generally irreversible.
Eli Hylands
Eli is the founder of Flow Crypto and editor of Flow News, covering crypto for New Zealanders.